Lucky7even Withdrawals Australia: Methods, Times and Verification
 Available in US
Lucky7even’s current Australia-localised payments page lists method-specific withdrawal processing labels rather than one universal payout time. Visa is shown at 1-3 banking days, Mastercard at 3-5 banking days and bank transfer at 5-7 banking days. A number of e-wallet and crypto rows are labelled instant. These are the site’s published processing labels, not guarantees that money will reach every account within exactly that period.
The withdrawal table needs careful reading. Its amount column is headed “Minimum Deposit” even while the withdrawal tab is active, and the bank-transfer row shows A$750 in that column. The label does not establish A$750 as a minimum withdrawal. Verification can also delay a withdrawal: Lucky7even’s current terms state that withdrawal requests remain pending until required KYC checks are completed.
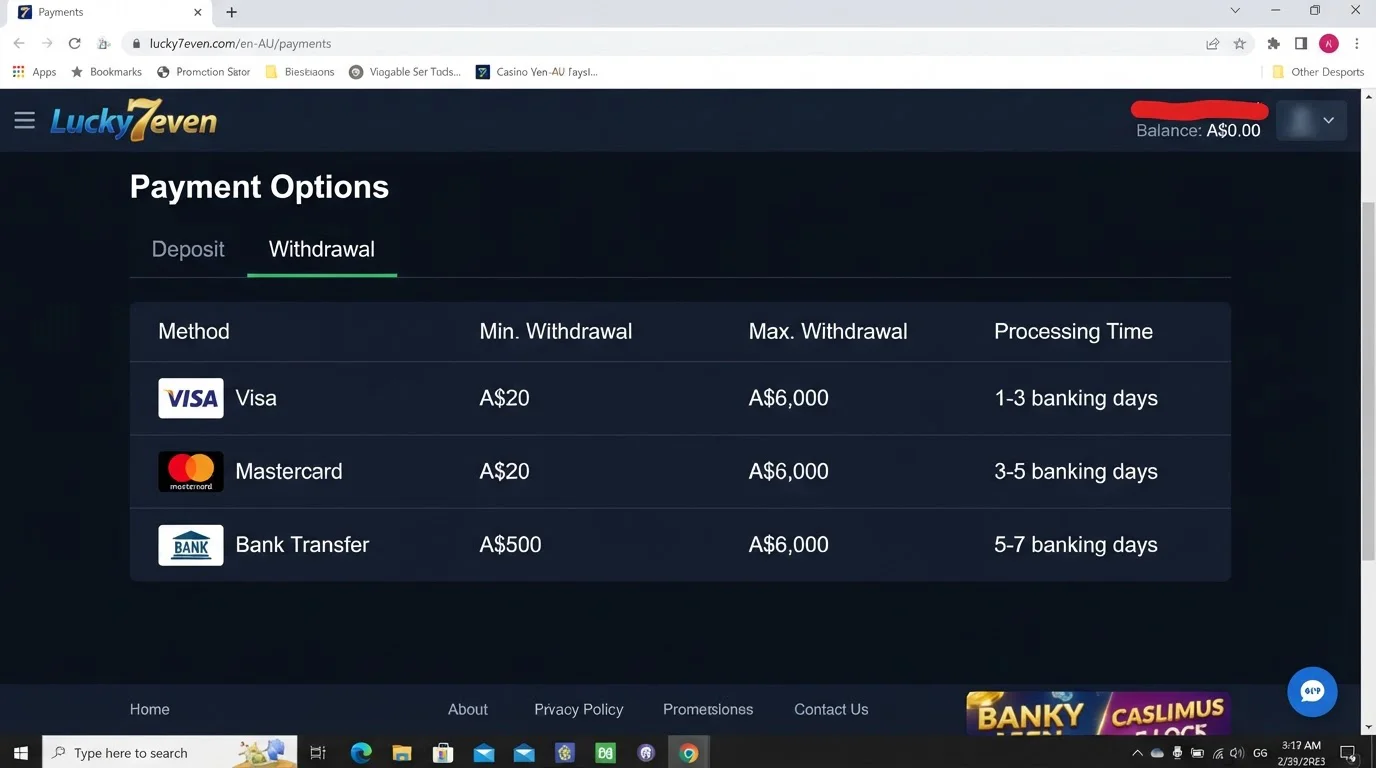
Table of Contents
- Current Lucky7even withdrawal times shown for Australia
- Why “instant” should not be read as a guaranteed instant cashout
- The A$750 bank-transfer figure: what the table does and does not prove
- KYC can become the real withdrawal bottleneck
- Cards, bank transfer, e-wallets and crypto compared
- A practical withdrawal checklist
- What user complaints can and cannot tell you
- Australian context: method availability is not the same as local legal approval
- Bottom line on Lucky7even withdrawals
Current Lucky7even withdrawal times shown for Australia
The public AU payments page separates deposits and withdrawals. On the withdrawal view, the clearest useful facts are the method-specific processing labels. Cards and bank transfer have banking-day windows, while a large group of wallet-style methods are presented as instant. Crypto rows are also shown as instant on the current table.
| Method | Type shown | Processing label shown | How to read it |
|---|---|---|---|
| Visa | Credit/Debit Card | 1-3 banking days | Published processing window, not a delivery guarantee |
| Mastercard | Credit/Debit Card | 3-5 banking days | Longer published card window than Visa |
| Bank Transfer | Bank Transfer | 5-7 banking days | Slowest of the three highlighted fiat examples |
| Skrill | E-wallet | Instant | Site table label |
| Neteller | E-wallet | Instant | Site table label |
| MiFinity and other listed wallets | E-wallet | Instant | Site table label, subject to account eligibility and verification |
| Bitcoin and listed crypto | Crypto | Instant | Site table label, separate from network settlement conditions |
The useful comparison is relative. Bank transfer is presented as slower than card payouts, while several e-wallets and cryptocurrencies are presented as faster. That does not establish an exact end-to-end time for a particular user because approval, verification, banking cut-offs and the receiving payment provider can sit outside the simple table label.
Banking-day wording also matters around weekends and public holidays. A range stated in banking days is not the same as the same number of calendar days, so a request submitted late on a Friday can span more elapsed time than a request submitted early in the working week. No separate Australian cut-off schedule is shown. Card and bank-transfer estimates should therefore be counted in business-processing days, while any account review or payment-provider delay can extend the total elapsed time.
Why “instant” should not be read as a guaranteed instant cashout
On a payment table, “instant” is a compact operational label. It can describe the payment method’s processing stage without accounting for every condition that happens before or after that stage. Lucky7even’s terms explicitly connect withdrawals to identity verification, so an account that still needs KYC review can remain pending even when the selected wallet row says instant.
There is also a practical difference between casino processing and final receipt. A payout can leave the casino workflow and still depend on the receiving provider. For cards and bank transfers, the site’s own table already acknowledges this by using banking-day ranges. For wallet and crypto methods, the instant label is best treated as a sign that the payment rail can be faster once the withdrawal is approved, not as a promise of immediate access to funds in all circumstances.
This distinction is especially useful when comparing methods. A user choosing a withdrawal route solely because one row says instant may be disappointed if the account is selected for verification. A better sequence is to check verification status first, then review the withdrawal methods actually displayed in the account, and only then compare the published processing labels.
The A$750 bank-transfer figure: what the table does and does not prove
The most unusual detail on the AU withdrawal table is the bank-transfer amount. The bank-transfer row displays A$750 in the amount column, while most fiat withdrawal rows display A$30. The problem is the column heading: the public page labels it “Minimum Deposit” even on the withdrawal view. That creates a source-level ambiguity.
Because the heading and context conflict, it would be too strong to rewrite A$750 as “the minimum bank-transfer withdrawal”. The verified statement is narrower: the current en-AU withdrawal table displays A$750 for bank transfer in its minimum column. The label does not cleanly tell us whether this is a withdrawal threshold, a reused deposit heading, or a presentation bug.
For a real cashout decision, check the logged-in withdrawal screen before choosing bank transfer. The amount shown there provides the clearest account-specific reference. The public table should be read together with its column labels because the A$750 figure appears under a heading that says “Minimum Deposit”.
KYC can become the real withdrawal bottleneck
Lucky7even’s current terms state that the operator may request additional documentation or a phone call as part of its KYC process, and that withdrawal requests remain pending until required verification steps are completed. The terms also list government-issued photo identification and proof of address among the documentation that can be requested.
That makes verification a separate timeline from the payment-method label. A Visa row showing 1-3 banking days does not mean an unverified account automatically completes the full withdrawal process in that period. The same principle applies to an e-wallet marked instant. If verification is triggered, the withdrawal can remain pending before the method-specific stage becomes relevant.
For readers who have not yet created an account, use accurate personal information and keep standard identity and address documents available. Do not send documents to unofficial contacts or third parties. For the full account-verification process, see Lucky7even registration and KYC.
Cards, bank transfer, e-wallets and crypto compared
Cards are the easiest reference point because the site publishes simple banking-day ranges. Visa is currently shown as faster than Mastercard. Bank transfer has the longest published range among those three familiar fiat routes. That may appeal less to users who prioritise speed, but a bank route can still be useful for someone who prefers direct account settlement and sees it as an available option after login.
E-wallets are presented differently. Skrill, Neteller, Ecopayz, Instadebit, MiFinity, MuchBetter, Pay4Fun, AstroPay and other wallet-style entries are labelled instant on the public withdrawal table. The list is broad, but availability on a public page should not be treated as a guarantee that every method will appear for every account. The live cashier is the final operational view.
Crypto is also listed with instant processing for several assets, including Bitcoin, Ethereum, Litecoin, Bitcoin Cash, Dogecoin and USDT. Crypto introduces a second layer of timing because blockchain confirmation and wallet handling are separate from the casino’s own processing label. It also introduces price volatility for assets whose value changes against AUD, so fixed Australian-dollar equivalents can become outdated quickly.
A practical withdrawal checklist
- Check your account verification status. If KYC is outstanding, resolve that before relying on any published payout time.
- Open the live withdrawal cashier. Compare the methods actually available to your account rather than assuming every public-table option is enabled.
- Read the processing label by method. Visa, Mastercard and bank transfer currently have different banking-day windows; many wallet and crypto rows are labelled instant.
- Do not infer a minimum from a confusing heading. In particular, the A$750 bank-transfer figure sits under a column labelled “Minimum Deposit” on the withdrawal table.
- Keep a record of the request. Note the submission time, method and amount so you can distinguish an expected processing window from an actual delay.
- Use official support if something falls outside the published flow. Avoid relying on forum posts or individual complaints as proof of what will happen to your own withdrawal.
What user complaints can and cannot tell you
Online casino reviews and complaint threads often focus on withdrawals because payout delays are highly visible to users. They can be useful as sentiment signals, especially when the same issue appears repeatedly. They are not reliable evidence that a specific withdrawal will fail, and they cannot establish the cause of an individual delay.
A complaint may reflect incomplete KYC, a payment-provider issue, a disputed bonus condition, an account investigation or a genuine service problem. Without the account record, the cause cannot be established from an anecdote alone. Current withdrawal terms and verification requirements provide a firmer basis for comparing the documented process.
Australian context: method availability is not the same as local legal approval
The presence of an Australia-localised cashier and AUD figures tells you what Lucky7even currently publishes for the AU interface. It does not establish that the operator holds an Australian local licence or that each service is authorised under Australian interactive gambling law. Those are separate regulatory questions.
If legal status matters to your decision, see Lucky7even licence and ACMA status. Payment-method availability and regulatory status are separate considerations.
Bottom line on Lucky7even withdrawals
Lucky7even gives Australian visitors a relatively detailed public withdrawal table. The strongest current comparisons are straightforward: Visa is shown at 1-3 banking days, Mastercard at 3-5 and bank transfer at 5-7, while numerous e-wallet and crypto methods are labelled instant. The table is useful, but its wording is not perfectly clean.
The A$750 bank-transfer figure should not be promoted as a verified minimum withdrawal because the amount sits under a column headed “Minimum Deposit” on the withdrawal tab. KYC is also a real dependency: the site’s current terms allow identity checks and say withdrawals can remain pending until required verification is complete. Taken together, those points make the best withdrawal strategy less about chasing the shortest label and more about checking your verification status, reading the live cashier and choosing a method whose displayed terms make sense for your account.
For the deposit side of the cashier, including A$30 fiat minimums and current funding options, see the Lucky7even payment methods. For the broader brand picture, return to the Lucky7even Australia review.
Published by the Lucky7even Casino team.